The deep dive
One Up On Wall Street
by Peter Lynch
18 min read · Original commentary by Lumina, written with AI
Peter Lynch gives ordinary investors a possible advantage, then makes them work to deserve it. Everyday knowledge can reveal promising businesses, but ownership requires more than liking a product. This deep dive explores how the book links observation, valuation, and patience—and where its confidence in individual judgment needs testing.
Prefer the quick version? Read the main learnings →♫ AI-generated voice · press play below to listen and read along; tap any passage to jump to it
01
An invitation to notice—and a demand to investigate
One Up On Wall Street is nonfiction investment guidance built around company analysis and personal experience. Lynch argues that individuals can sometimes outperform professional investors. Their opening advantage may come from ordinary life: serving customers, using products, watching suppliers, or knowing an industry. They need not discover every winner or predict the next market turn.
Yet the book offers no shortcut from recognition to profit. A useful product may belong to an indebted company. A strong business may already command an unreasonable price. An expanding chain may run out of room. Lynch’s invitation is therefore conditional: notice what others miss, then investigate what your own enthusiasm overlooks.
Readers should expect practical reasoning rather than a complete theory of markets. Company examples, financial measures, autobiographical episodes, and warnings about investor behavior carry the argument. The central intellectual question is whether limited, local knowledge can become a sound decision about an uncertain future.
Lumina’s reading is that the book distributes confidence unevenly. It trusts people’s ability to begin research more than it trusts their first conclusions. That distinction makes its promise demanding rather than merely flattering. The ordinary investor’s freedom matters only when paired with a willingness to question the apparent opportunity.
Illustrated key idea
Daily life can suggest investments, but it cannot finish the work02
What kind of advantage can an ordinary investor actually have?
Lynch’s challenge to professional authority is narrower than it first appears. He does not argue that amateurs know more about every company. He argues that useful knowledge can appear outside financial institutions, while institutional rules can delay action. An employee may notice improving orders. A customer may recognize a store’s appeal. A large fund may be unable to buy a small company in a meaningful amount.
These are different advantages. One concerns access to clues; another concerns freedom to act. Neither establishes that the stock is worth buying. The investor must still connect a business change to future profits and compare those prospects with the price demanded today.
The stakes are both financial and personal. Lynch’s tenbagger—a stock that increases tenfold—makes large winners central to his approach. A few exceptional investments can compensate for several mistakes. But that possibility also creates a temptation: imagining exceptional returns can weaken attention to ordinary risks. The book counters this temptation with questions about debt, expansion, earnings, and money needed for living expenses.
Its approach replaces an enormous prediction problem with several smaller judgments. Instead of forecasting the entire market, ask how a company earns money. Instead of predicting a precise future price, ask what would support higher profits. Instead of seeking certainty, identify which developments would weaken the case.
Lumina interprets this as a move from broad confidence to specific accountability. A claim about an economic boom can remain vague. A claim that a retailer can reproduce profitable stores must face evidence about new locations, costs, financing, and demand.
The boundary matters: smaller questions are not easy questions. Public information can be incomplete, future growth remains uncertain, and prices can depart from business value for years. Lynch offers a way to organize judgment, not a guarantee that investigation produces an advantage. His acceptance of funds for people without the time or interest to research is part of the argument, not an embarrassing exception.
03
Local knowledge is a clue, not a conclusion
The first major idea is that firsthand knowledge can help an investor ask better questions before it supplies better answers. Lynch treats ordinary experience as a source of research leads. Its value comes from contact with actual business activity, not from the reassuring feeling of familiarity.
The L’eggs example makes that distinction concrete. The idea began with a shopper rather than an analyst. Lynch’s wife found the stockings good and easy to pick up with the groceries, and what she had seen put Hanes, their maker, on his radar. Only the research he then did turned a shopper’s preference into a reason to invest. The observation mattered because it suggested a business advantage worth examining. It did not, by itself, establish the company’s value or financial strength.
Lumina’s interpretation is that the method requires several changes of scale. Start with a product or service. Ask whether its appeal is shared beyond your own experience. Then ask whether it contributes enough to the whole company to matter. Finally, examine whether the company can turn demand into profits that benefit shareholders. Each step blocks a different leap of faith.
This helps explain why knowing a product well can coexist with misunderstanding its stock. Customers experience usefulness and price. Shareholders also depend on costs, financing, competition, management decisions, and the purchase price of their shares. A customer’s satisfaction is relevant evidence, but it covers only part of the business.
The book also widens what counts as promising evidence. A company need not invent exciting technology to benefit from it. ADP illustrates a business using computers to provide payroll services while benefiting from cheaper equipment. The investment question shifts from technological novelty to the economics of delivering a service. Likewise, a dull industry can contain a strong operator without attracting a rush of new competitors.
That shift has an important implication. Research should follow the source of profit, not the source of attention. A growing industry may create fierce competition. An unfashionable service may have recurring demand and a protected local position. Neither glamour nor dullness settles the case; both must be translated into business consequences.
The boundary is the quality of the observation. One busy visit does not establish lasting demand. One complaint does not establish decline. Lynch acknowledges that isolated opinions can mislead and that investors can miss opportunities within industries they know intimately.
Local knowledge therefore works best as a way to focus research. It can identify what deserves attention and which questions deserve priority. It cannot remove the need for financial analysis. The next step is to establish what kind of opportunity the clue points toward—and what evidence that kind of opportunity requires.
04
The right question depends on the business—and the price
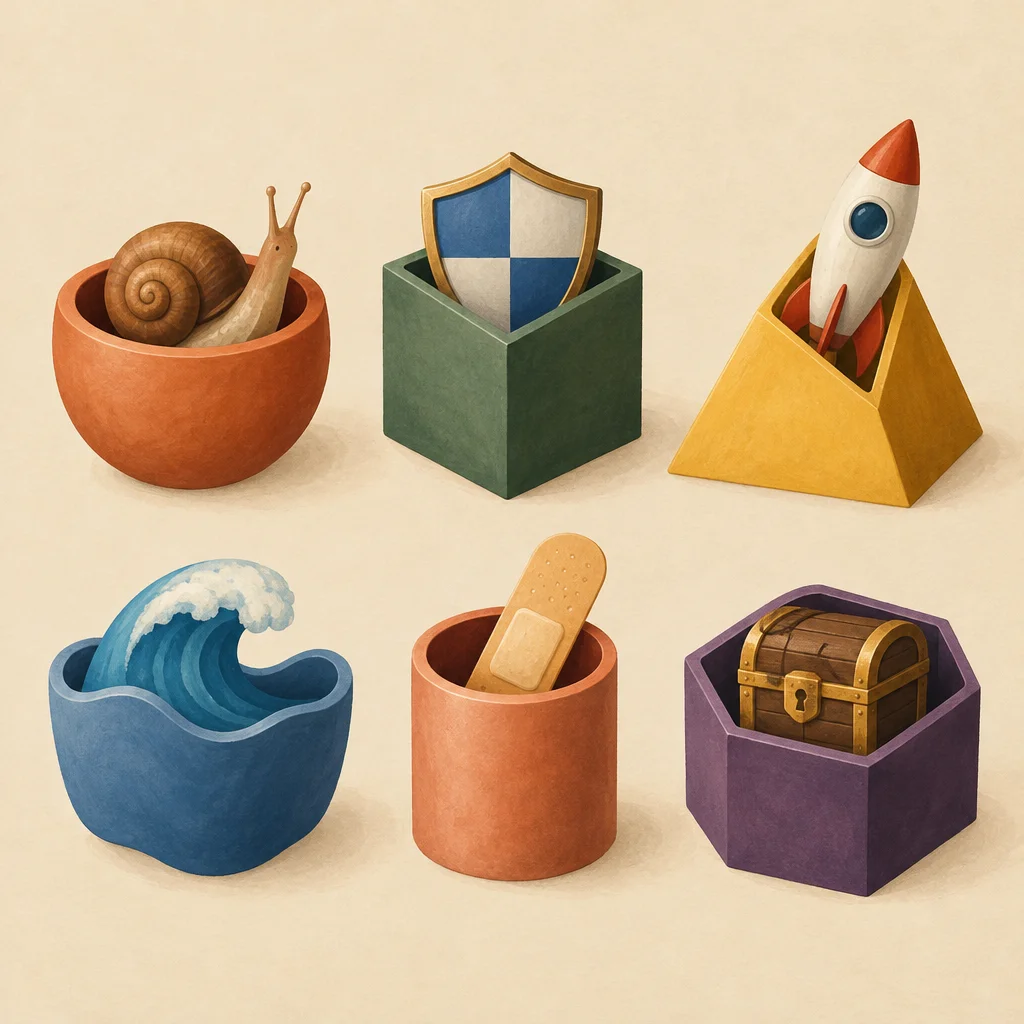
Before asking how much a stock might rise, Lynch asks what could produce the return. His six categories separate those possibilities. Slow growers offer limited expansion and often attract investors through dividends. Stalwarts are established companies growing at a moderate pace. Fast growers depend on more rapid expansion. Cyclicals have profits that rise and fall with recurring changes in business conditions. Turnarounds need to overcome serious trouble. Asset plays draw attention because their holdings may be worth more than investors recognize.
These distinctions change the order of inquiry. With an expanding chain, ask whether additional locations can earn attractive profits. With a distressed business, ask whether it can meet its obligations long enough to improve. Future success cannot help current shareholders if repayment demands bring the company down first.
For an asset play, the challenge is to work from apparent wealth toward what shareholders might actually benefit from. A recorded equipment value may exceed its resale proceeds. Borrowing may absorb much of the value of a property or subsidiary. Finding something valuable inside a company is therefore the beginning of an argument, not its completion.
Price adds a second test to every category. The price/earnings ratio, or P/E, expresses the share price as a multiple of yearly profit per share. Lynch does not treat a smaller number as an automatic bargain. In a cyclical business, unusually strong profits can temporarily make the ratio look low. If those profits then fall, the apparent cheapness may disappear without any increase in the share price.
A high ratio presents the opposite question: how much future progress has the buyer already paid for? A company may operate well yet deliver disappointing investment results because its price required even better performance. The relevant comparison is not simply between good businesses and bad ones. It is between a plausible future and the expectations built into today’s price.
Lumina interprets classification and valuation as two safeguards against different mistakes. Classification asks whether the investor expects the right kind of result. Valuation asks whether that result would justify the cost. Neither can stand alone.
The accounts provide a further check. Profits may look healthy while necessary spending consumes much of the cash the business generates. Debt schedules can limit its room to respond. Those constraints matter even when the product is popular and the growth plan sounds convincing.
The boundary is that these tools organize uncertainty rather than remove it. A business can move between categories or fit several at once. Earnings estimates can fail. Lynch’s useful demand is to connect the proposed return to observable developments, then examine both the resources and the price required to pursue it.
Illustrated key idea
A good stock idea needs a story that can be checked05
Patience means staying responsive, not staying still
The third idea concerns time. Lynch favors patient ownership, but his patience depends on continued scrutiny. Holding a stock for years is not enough. The reason for owning it must remain credible, and the investor must remain financially able to wait.
This links two parts of the book that might otherwise seem separate: personal preparation and company research. Money needed soon does not become suitable for stocks because the investor finds a compelling business. Even a sound company’s shares can remain depressed for years. An investor forced to sell may never benefit from the business development originally anticipated.
Lumina’s interpretation is that the ability to wait is partly built before the purchase. It depends on cash needs, risk tolerance, and the size of the commitment. Emotional discipline is harder when a declining quotation threatens essential expenses. Lynch’s emphasis on temperament therefore belongs beside financial analysis, not beneath it as a motivational afterthought.
Once invested, patience has to coexist with revision. The book recommends checking reports, earnings, operations, and future growth prospects every few months. A fast grower may approach saturation. A recovery may finish, leaving an ordinary business that needs a different valuation. A company’s category is not a permanent identity.
This explains Lynch’s resistance to automatic selling rules. A stock’s doubling does not establish that its opportunity is exhausted. A steep decline does not establish that it has become cheap. Neither movement tells the investor enough about future earning power or current valuation. Price matters, but its direction alone is not an argument.
The distinction becomes especially important when growth slows. A company can keep increasing profits while investors reduce the earnings multiple they will pay. Business progress and stock performance may then diverge. The investor must ask both whether profits can continue growing and whether the valuation remains reasonable.
Patience also has limits. Staying committed because evidence remains favorable differs from waiting for the stock to return to one’s purchase price. That personal reference point says nothing about the business. Equally, repeated outside warnings should prompt investigation rather than either automatic obedience or stubborn dismissal.
Lynch’s opposition to options for ordinary investors sharpens this argument about time. An option can expire before an otherwise sound judgment pays off. Ordinary share ownership has no comparable expiration deadline, though business failure can still destroy its value.
The implication is not simply to hold longer. It is to align the investment’s time needs with the investor’s resources, then remain open to disconfirming evidence. Patient ownership requires both endurance and permission to change one’s mind.
06
How the stories teach—and what they cannot prove
Contains plot details — open to read
The book persuades through examples that expose gaps between a plausible idea and a complete investment case. Its personal voice gives mistakes analytical work to do. They are not merely admissions of fallibility; they show how a particular judgment went wrong.
La Quinta and Bildner’s offer a useful contrast, and the difference between them is the kind of evidence each offered. For La Quinta the evidence reached beyond a single site: the motels were cheaper to build, the same format had already been repeated successfully in new locations, and the financing suited a capital-hungry business. For Bildner’s, the evidence that mattered to Lynch came from the original shop, and it left the expansion question unresolved. He liked the product, that shop made money, and he bought on that basis without finding out whether the format travelled. The answer came from the business itself rather than from research, as the new locations failed and their losses drained the company’s resources. The contrast makes repeatability a concrete business question rather than a vague hope about growth.
Another anchor is Flying Tiger Airlines. Lynch’s early investment succeeded, but the cause differed from his original expectation. Lumina reads this as an important challenge to judging reasoning by results alone. A profitable purchase can rest on a mistaken explanation. If investors learn only that they made money, they may repeat the weak reasoning without repeating the luck.
The book’s short, plain-language investment explanation serves a different purpose. It asks the investor to connect the opportunity, required developments, and risks. Its force lies in exposing missing links. If the case cannot explain how a company’s appeal becomes earnings, more detail may conceal rather than solve the problem.
Financial examples also make analysis approachable, though simplification requires care. In the Ford discussion, the calculation of cash after debt excludes short-term borrowing because Lynch assumes other assets cover it. That assumption matters. A useful calculation can mislead when detached from the judgment that makes it appropriate.
The evidence remains largely illustrative. Selected winners and mistakes can clarify mechanisms, but they do not establish how often ordinary investors can identify them beforehand. Lynch acknowledges that some spectacular historical returns assume unusually favorable timing. His admissions strengthen the book’s credibility without turning its examples into a controlled test.
Lumina’s assessment is that the book is strongest as training in questions. The original’s fuller cases offer room to examine how claims are built, where numbers depend on assumptions, and how confidence survives—or fails—when new facts arrive.
07
Does the method ask too much of the person it empowers?
Lumina’s strongest objection is that Lynch’s invitation may be easier to accept than his discipline is to sustain. Discovering a promising business can feel immediate and enjoyable. Checking debt terms, questioning growth, comparing valuations, and reviewing holdings takes repeated effort. The ordinary investor may possess freedom from institutional pressures without possessing the time or judgment to use that freedom well.
The book itself makes this objection substantial. Categories can change. Assets may disappoint. Earnings forecasts can miss. A company can recover without existing shareholders benefiting, especially when new shares dilute their ownership. These complications sit some distance from the appealing idea of recognizing a winner while shopping.
There is also an evidence problem. Memorable winners show what was possible, not what a new investor should expect. Looking backward makes successful expansion visible. Looking forward requires separating durable strength from temporary popularity before the outcome is known. The book’s examples do not establish a general success rate for its intended audience.
The strongest reply is also available within Lynch’s argument. He does not treat stockpicking as an obligation. Funds remain a valid choice for those unable or unwilling to research. He recommends judging results after expenses against an appropriate benchmark. The method therefore includes a test of whether the effort earns its place.
A second tension concerns forecasts. Lynch discourages predicting the market while asking investors to assess future company earnings. That is not freedom from prediction altogether. Lumina interprets the distinction as one of scope and accountability. A company-level expectation can name costs, customers, financing, and expansion plans that an investor can monitor. It remains uncertain, but it is less diffuse than a call about the entire market.
The fairest conclusion is neither that amateurs have no advantage nor that professionals are unnecessary. Lynch identifies circumstances in which individuals may have useful clues and greater flexibility. Whether those advantages survive mistakes, costs, and uneven judgment remains an open question for each investor. His confidence is most defensible when read alongside his permission to wait, admit uncertainty, or choose a fund.
08
Join observation, explanation, and review into one decision
The book’s ideas become clearer when treated as parts of one continuing decision. Observation identifies something worth studying. Classification identifies the relevant questions. Valuation tests what the price already assumes. Financial analysis tests whether the company can survive and benefit. Later review asks whether the explanation still fits.
Consider an imagined example created by Lumina: a customer notices that a small retailer’s branches are consistently busy. That observation suggests demand, but leaves several possibilities open. Existing stores may be profitable while new stores cost too much. Crowds may reflect discounts that weaken margins. Expansion may require borrowing the company cannot comfortably repay.
Calling it a fast grower would not solve these questions. It would make them more urgent. The investor would need evidence of profitable replication, room for further expansion, and a price that does not assume flawless success. Later, more branches would not automatically confirm the case. Their financial performance would matter.
This hypothetical connects the book’s three central disciplines without making daily life into a constant stock hunt. The relevant habit is separating what one has seen from what one has inferred. A crowded shop is an observation. Sustainable earnings growth is a further claim. An attractive investment at today’s price is another claim again.
A practical application is to preserve those distinctions in a brief written case. Identify the expected source of return, the financial constraint, and the evidence that would prompt reconsideration. Lynch’s approach also requires a personal question: can this money remain invested through an unfavorable period?
None of this supplies a recommendation to buy a particular stock. It offers a way to make reasoning visible. That visibility helps connect the initial decision with later action, reducing the temptation to invent a new justification whenever the old one weakens.
Illustrated key idea
Different businesses require different tests09
Discuss the promise without overselling the proof
A useful conversation about One Up On Wall Street begins by separating its promise from its procedure. The promise is that individuals may find opportunities professionals overlook. The procedure is demanding company research, sensible valuation, and continuing review. Agreement with the promise does not settle whether a particular person should pick stocks.
When someone describes the book as advice to buy familiar companies, ask what familiarity establishes. It may reveal customer appeal or industry change. It does not establish financial survival, profitable expansion, or a reasonable share price. That distinction opens a richer discussion than either celebrating common sense or dismissing amateur investors.
Another productive disagreement concerns patience. One reader may hear a warning against panic; another may worry about rationalizing losses. Both concerns fit the book. The deciding issue is what evidence supports continued ownership and what would overturn it.
Be candid about the limits of this account. It explains the book’s reasoning through reviewed summaries, not a firsthand assessment of every page. You can discuss its central distinctions without claiming to have checked every example. The most revealing follow-up question is practical: what would count as evidence against your preferred interpretation of Lynch’s method?
What to remember
Separate noticing demand from establishing value.
Lynch gives everyday experience a legitimate role in finding candidates. It remains necessary to test whether demand affects company profits, can persist, and is already reflected in the price. The advantage lies in a better starting question, not an exemption from research.
Let the source of return determine the evidence.
Expansion, recovery, dividends, and overlooked assets require different tests. A company label helps only when it directs attention toward the relevant risk. Financial survival may dominate a turnaround case, while repeatable profitability and remaining opportunity matter more for an expanding business.
Build the ability to wait, then keep questioning.
Patient ownership needs money that can remain invested and a business case that still holds. Lynch rejects both panic-driven selling and loyalty to a broken explanation. Time helps only when the investor can endure uncertainty and continues checking what the company must achieve.
Bring it into conversation
Talk about the book
Where does useful firsthand knowledge become overconfidence?
Lynch’s argument is strongest when local experience reveals a specific business change. It weakens when familiarity becomes a reason to skip questions about the whole company. Lumina’s view is that an observation should increase curiosity before it increases commitment.
Take it further: Which additional fact would most change your interpretation of a busy store or popular product?
Can rejecting market forecasts coexist with estimating company growth?
The book still requires judgments about the future. A fair defense is that company expectations can be tied to concrete developments and reviewed against results. That makes them more testable, not certain.
Take it further: What would make a company forecast genuinely accountable rather than merely more detailed than a market prediction?
When is choosing a fund the more independent decision?
Lynch values independence, but does not equate it with personally selecting stocks. If research takes too much time or results fail to justify costs, using a fund can follow his reasoning rather than reject it.
Take it further: How would you judge whether stockpicking earns its place without letting one lucky success settle the question?
Keep in perspective
This account draws on reviewed summaries, not the book’s complete text. The supplied material supports analysis of Lynch’s method and examples, but not an independent test of its performance. No external criticism or current market evidence is available here. Historical financial and housing claims should not be treated as verified guidance for today’s circumstances, and the discussion offers no personalized investment advice.