The deep dive
The Big Short
by Michael Lewis
18 min read · Original commentary by Lumina, written with AI
- Topic: Business
A handful of investors see danger inside mortgage securities that powerful institutions consider safe. Michael Lewis follows their efforts to understand the danger and bet against it. This deep dive examines the book’s larger challenge: why expertise, prices, and private rewards failed to keep financial risk under control.
Prefer the quick version? Read the main learnings →♫ AI-generated voice · press play below to listen and read along; tap any passage to jump to it
01
A financial puzzle with human guides
The Big Short is narrative nonfiction about investors who questioned the American subprime mortgage boom. These mortgages went to borrowers whose ability to repay could be uncertain. Banks turned the loans into securities, which allowed investors far from the original lending decision to buy their promised payments.
Lewis follows several routes into this market. Steve Eisman brings anger about consumer lending and a willingness to confront executives. Michael Burry studies mortgage documents through solitary, detailed research. Cornwall Capital looks for inexpensive bets on outcomes that market prices seem to dismiss. Their differences matter: the book does not present independent thinking as one personality type.
Readers should expect financial explanation carried by conflict rather than a complete institutional history. Understanding a contract becomes urgent because someone must decide whether to buy it, keep paying for it, or trust the bank behind it.
Lumina’s reading is that the central puzzle concerns organized ignorance. How could institutions employ specialists, publish ratings, and trade constantly without controlling the danger they shared? The book invites readers to distinguish having information from having reasons to act on it.
Illustrated key idea
The crisis followed the payoffs, not just the appetites02
What made disbelief more valuable than expertise?
The book’s central question is not simply why house prices or mortgage bonds were misjudged. It asks why an entire financial chain could keep rewarding activity that depended on fragile loans. A lender, bond arranger, rating agency, insurer, and investor might each examine a different part. Yet no reassuring judgment about one part could make the borrower’s payments more affordable.
Lewis approaches this question through investors who ask what must happen for a security to work. Burry looks beneath broad measures of loan quality. FrontPoint examines lending practices and the assumptions behind ratings. Cornwall asks whether securities described as diversified could fail together. These investigations shift attention from institutional reputation to the conditions required for repayment.
One important argument concerns refinancing. Research promoted by Greg Lippmann suggested that borrowers could get into trouble even without a dramatic fall in house prices. If they depended on rising values to replace unaffordable mortgages, slower appreciation could be enough. The distinction matters. A system can be unstable because it needs unusually favorable conditions, not only because it cannot survive an extreme disaster.
The stakes extend beyond predicting defaults. Investors need a contract that expresses their view, enough money to maintain it, and a solvent institution to honor it. The book therefore separates three questions: Is the analysis sound? Can the trade survive? Can the financial system absorb the result?
Lumina interprets this separation as the book’s intellectual engine. Expertise fails when it becomes confidence in a label or a familiar model instead of inquiry into underlying conditions. But disbelief is not automatically wisdom. The protagonists must investigate, seek objections, and confront gaps in their own understanding. Their skepticism matters because it does work, not merely because it opposes consensus.
03
Follow the rewards before judging the judgment
Lewis’s strongest explanation is that greed alone cannot account for the disaster. The more precise issue is how institutions rewarded decisions before their full costs became visible. This changes the question from whether people wanted money to what they were paid to do, and whose money remained at risk afterward.
Consider the lending chain. A lender that keeps a mortgage has a direct interest in years of repayment. Selling that mortgage changes the lender’s position. It can collect income from making the loan while moving much of the later repayment risk elsewhere. The book links this arrangement to weakening standards. It does not establish that every sold mortgage was bad; it shows why selling loans could remove an important restraint.
Eisman’s earlier work with Vincent Daniel makes the argument concrete. Daniel finds that lenders’ reported profits rely on assumptions about future loan income. In mobile-home lending, some apparent early repayments turn out to involve defaults and partial recovery. The accounting category suggests one event while the underlying transaction reveals another. Growth can then help maintain the appearance of strength rather than confirm it.
The same lens applies further along the chain. A CDO manager paid according to the volume of assets managed has a reason to expand. That reason differs from an investor’s need to avoid credit losses. Rating agencies face commercial pressure from the firms whose securities they assess. These are not identical conflicts, but they point in the same direction: scrutiny can obstruct the activity that generates current income.
Lumina’s interpretation is that incentives connect conduct that might otherwise look like a collection of unrelated mistakes. Nobody needs to coordinate every decision for the decisions to reinforce one another. Loan production feeds securities production. High ratings encourage purchases. Purchases support further production. Each participant can point to another participant’s approval.
This reading also explains why the book resists a simple division between clever people and foolish people. A capable person can work within a system that makes narrow success compatible with wider harm. Technical skill may improve a transaction without correcting its purpose or its hidden exposure.
There is a boundary to this explanation. An incentive identifies a pressure, not a proven motive in every case. FrontPoint’s members themselves disagree about the balance between dishonesty and self-deception. Lewis’s broader claim about public ownership separating rewards from losses is an argument about institutional design, not a complete demonstration of every cause of the crisis. The useful insight is narrower and stronger: judgment cannot be assessed apart from who benefits when it is accepted.
04
New packaging did not create new safety
The second central idea concerns the gap between a security’s structure and the risk that supports it. Financial packaging can change who receives payments first. It cannot, by itself, make the underlying borrowers more able to pay. Lewis’s account becomes clearer once those two functions are kept separate.
A mortgage bond does not give every holder an equal claim on incoming money. Its contract sets priorities among groups of investors; each group holds a tranche. Senior holders have others beneath them bearing the initial damage when borrowers fail to pay. Their safety therefore depends on the size of that cushion. Once enough losses use it up, payment priority no longer keeps them beyond reach.
CDOs add another level. Banks gather lower-rated pieces of mortgage bonds and divide the resulting payments into new layers. Many upper layers receive very high ratings. The critical question is whether the ingredients offer genuine protection through different sources of risk, or whether they remain exposed to the same housing conditions.
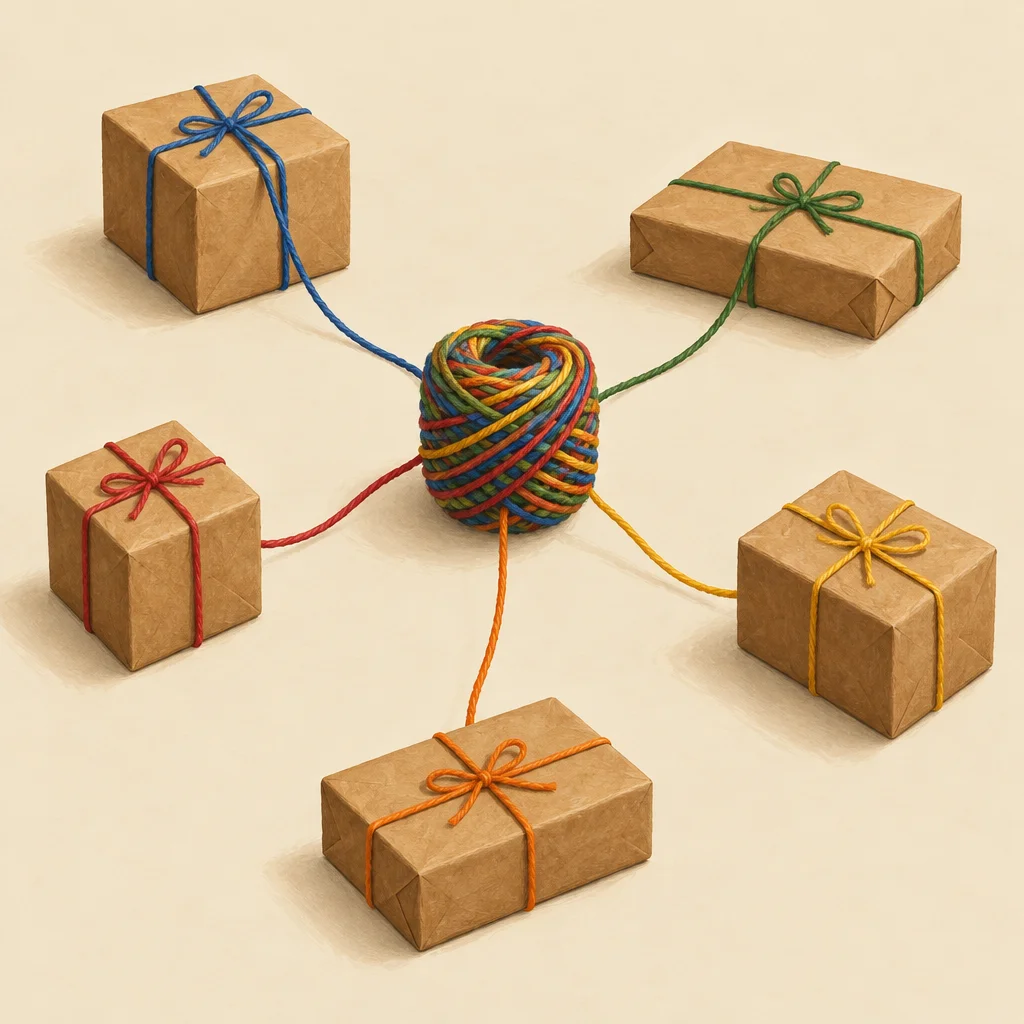
The book’s skeptics focus on that shared exposure. Diversification means that different holdings do not all depend on the same outcome. A large number of securities can still be poorly diversified if similar pressures threaten them together. Geographic spread offers limited comfort if borrowers across those places depend on continued price growth and easy refinancing.
To assess a rating, the investigators must ask which possible futures its calculations allow. FrontPoint discovers that declining home values lie outside the range of one S&P model. That exclusion matters before any calculation begins: a test cannot show resilience against a condition it cannot represent. A separate weakness concerns higher interest charges. Models count the extra money due without allowing for the greater danger that borrowers will not pay. Lumina reads these findings as failures to connect projected income with the conditions needed to collect it.
Synthetic CDOs introduce a distinct issue. They use credit default swaps to create exposure to mortgage bonds without requiring another mortgage to be made. A swap involves recurring payments in exchange for compensation if specified credit losses occur. Repeated contracts can therefore create multiple financial exposures linked to the same underlying loans. This is not simply another way of dividing a fixed stream of mortgage payments.
Lumina reads these mechanisms as a challenge to the comforting appearance of distance. Each new wrapper can make the original borrower seem less relevant, even as repayment still depends on that borrower or on closely related housing risks. Complexity can distribute claims while leaving their common weakness intact.
The boundary matters here too. The book does not prove that all layering, insurance, or complex securities are useless. Its criticism concerns structures whose ratings and prices fail to reflect their actual dependencies. The right question is not whether a product has several layers. It is what those layers protect against, which assumptions make that protection work, and what happens when many holdings fail together.
Illustrated key idea
More layers did not mean more independence05
Being right was only the first obstacle
Contains plot details — open to read
The third idea follows from the first two: recognizing bad incentives and hidden exposure does not guarantee a successful investment. The skeptics still need to survive the market they distrust. Lewis makes this practical problem central rather than treating the eventual outcome as proof that the path was easy.
Burry’s swaps require continuing premium payments. Those payments reduce his fund’s resources while he waits. His investors can see costs and unfavorable valuations before they see the gains he expects. Their patience is not unlimited, and their requests to withdraw money can threaten the position itself. A forecast has a time horizon; the people financing it may have another.
Valuation creates a second problem. Because the contracts trade infrequently, there is no simple, independent price available at every moment. Dealers assign values that Burry disputes. He reports that counterparties will not sell him the contracts he wants at the values they assign to his existing holdings. That mismatch gives substance to his concern. It does not, by itself, establish every allegation of deliberate manipulation.
Burry responds to withdrawal pressure by restricting access to roughly half his investors’ money. Lewis’s account preserves a genuine conflict. Keeping the position intact may protect its expected value, but investors have legitimate objections: the contracts can be sold, even at prices Burry considers wrong. Lumina reads this as a clash between analytical conviction and authority over other people’s capital. Future success does not erase that clash.
Counterparty risk adds a third obstacle. A counterparty is the institution on the other side of a contract. If the institution owes money but fails before paying, the correct forecast may not deliver the expected return. Cornwall’s concern about Bear Stearns makes this danger concrete. Selling winning positions reduces dependence on the bank’s survival, rather than merely marking the end of a successful prediction.
The book’s financial victories therefore widen into fear. Burry earns enormous profits but remains estranged from investors and eventually closes Scion. FrontPoint’s success does not remove its exposure to a vulnerable financial owner. Cornwall questions where wealth can remain safe when banks themselves appear threatened. These outcomes turn a story of detection into a story about dependence.
The implication is not that patience always defeats a mistaken market. Every losing investor could make that claim. The narrower lesson is that evidence, funding, contracts, and payment capacity are separate requirements. The book supplies strong examples of sound analysis under pressure, not a general license to ignore criticism. Its force comes from showing how even justified conviction can carry real obligations, uncertainty, and personal damage.
06
How character makes the machinery visible
Contains plot details — open to read
Lewis explains finance by placing technical questions inside human disagreements. A definition matters because someone doubts a trader, challenges a rating, or fears losing investors’ money. This method gives otherwise abstract mechanisms a practical test: what does this feature allow someone to do, and who bears the consequences?
The contrasting protagonists serve that method. Burry’s tool is arithmetic done alone: he asks what the figures record and what rewards the conduct that produced them. Eisman’s confrontations expose the gap between confident explanations and underlying knowledge. Cornwall’s search for unlikely outcomes directs attention toward risks that prices appear to discount. Lumina’s interpretation is that these perspectives act as different investigative tools rather than interchangeable portraits of unconventional genius.
There are also limits to what any protagonist knows. Cornwall does not initially understand that its selected CDOs are synthetic, despite seeking expert help. Eisman struggles to locate banks’ exposures. Published critics fare no better: Jim Grant and Dan Gertner go looking in the CDO paperwork for what the securities actually hold and come away unable to say. Such gaps prevent the narrative from supporting an all-knowing outsider myth.
Howie Hubler provides a particularly sharp contrast. He buys roughly $2 billion in protection against subprime mortgages while selling protection on about $16 billion in highly rated CDOs to finance the cost. His eventual disaster shows why spotting weakness in one security does not establish control over the whole trade. The larger position carries related housing exposure behind a safer label.
The narrative’s movement from investment gains to systemic distress also changes its meaning. In Lumina’s reading, the apparent success story becomes an inquiry into whether anyone can remain safely outside the damage. The protagonists’ emotional responses complicate the financial scoreboard rather than decorate it.
The afterword further qualifies narrative authority. Greenblatt explains the redemption pressure behind his dispute with Burry and criticizes Burry’s communication. Xu and Greenberg also challenge aspects of their portrayals. These responses do not resolve every disagreement. They remind readers that a compelling account has selected viewpoints. Lewis’s own discomfort at being treated as a policy authority reinforces the distinction between making a system understandable and possessing a complete explanation of it.
07
Can the winners diagnose the whole disaster?
Contains plot details — open to read
Lumina’s strongest fair objection is that the book’s chosen viewpoint can make profitable insight carry too much explanatory weight. Investors who found a winning trade are powerful guides to mispriced securities. They are not automatically the best guides to every borrower’s circumstances, every regulatory decision, or the full social damage of collapse.
This matters because narrative access shapes moral attention. We learn about premiums, withdrawal demands, trading agreements, and the stress of maintaining positions. Borrowers often become visible through the loans that investors examine. The asymmetry can make a systemic disaster feel most immediate through the anxieties of people positioned to profit from it.
The strongest reply is that the focus serves a specific inquiry. These investors have to discover who is accepting mortgage risk and why. Following them reveals mechanisms that a broader survey might describe less clearly. Lewis does not present their financial rewards as protection from the disaster, and their own dependence on fragile institutions undermines a simple celebration of winners.
A second tension concerns complicity. FrontPoint recognizes that buying swaps helped supply the synthetic CDO machinery. Exposing bad securities and helping create further exposure can be parts of the same transaction. Lumina’s interpretation is that this connection unsettles any clean opposition between truth-telling outsiders and a corrupt system.
Yet the opposite judgment would also be too simple. Showing that a trade helped sustain a mechanism does not prove that the traders intended the wider harm or bore equal responsibility with every other participant. Analysis should separate awareness, incentive, action, and consequence rather than compress them into one moral verdict.
Finally, the book’s explanations vary between error and misconduct. Its protagonists disagree about whether they are confronting delusion, incompetence, or fraud. Its strongest overall reply is institutional: incentives can make these failures reinforce one another without one motive explaining everything. Its unresolved boundary is causal precision. The supplied account supports a forceful diagnosis of linked weaknesses, but not a measured allocation of responsibility across the entire crisis.
08
Three questions that travel beyond the trading floor
The book’s ideas connect through three practical questions: What produces the promised payment? Who benefits before the outcome is known? What must remain intact for the promise to be honored? These questions join loan quality, incentives, and counterparty dependence without reducing them to one vague warning about risk.
The first question concerns evidence. A rating compresses a judgment into a convenient label. Compression can help people decide, but it can also hide the assumptions they need to examine. In the book, reading loan documents and checking lending practices offer ways to test whether the label fits. The application is to ask for the reason behind a classification, not to reject classifications automatically.
The second concerns moral hazard: an arrangement in which someone can benefit from taking risks while others bear much of the loss. Lewis’s account of loan sales and financial compensation gives that term concrete meaning. Lumina’s extension is that responsibility should be examined across time. Early rewards can remain private even when later damage spreads widely.
The third concerns dependence. Protection against one failure may introduce reliance on another institution. Cornwall’s trading agreements show why moving risk is different from removing it. The relevant question becomes whether the new holder can perform when the protection is most needed.
An imagined example created by Lumina helps distinguish these points. Suppose several guarantees protect different projects, but every guarantor depends on one source of funding. The projects may differ, and the guarantees may be valid, yet the shared funding weakness remains. Counting documents would not reveal that dependence.
These are habits of inquiry, not investment instructions. The book does not establish that contrarian trades are generally attractive or that complex products are always dangerous. Its more useful contribution is a way to test reassuring claims against cash flows, rewards, and connected obligations.
Illustrated key idea — contains plot details
Illustrated key idea
Correct didn’t mean comfortable or survivable09
How to discuss the book without flattening it
A strong conversation can begin by separating the book’s investment puzzle from its institutional argument. The puzzle asks how a few investors identified mortgage weakness. The argument asks why others could benefit from producing, approving, or holding exposure to that weakness. Solving the first does not settle every part of the second.
Another useful distinction is between skepticism and certainty. The protagonists challenge ratings, but Cornwall also questions its own success and seeks opposing arguments. Burry has detailed evidence, yet investors can reasonably question timing and access to their money. A discussion becomes richer when conviction and accountability remain in view together.
If someone describes the book as a story about greed, ask what that explanation leaves unexplained. Lewis’s emphasis on incentives concerns the route from wanting a reward to receiving it without bearing the full consequences. That is a more specific claim and offers more room for disagreement.
It is also worth asking what the narrative’s focus helps readers see and what remains outside it. Lumina’s view is that character-driven explanation makes financial mechanisms easier to grasp while leaving a need for broader perspectives. Readers can discuss that trade-off without pretending to know every omitted history. The reason to read the original is to encounter the pressure, personality, and uncertainty through which the argument develops.
What to remember
Inspect the path from reward to responsibility.
Lewis’s argument becomes sharper when greed is treated as a starting point, not an explanation. Ask when income is earned, who keeps exposure, and who absorbs later losses. Those details connect individual decisions to the larger financial chain.
Separate protection from the assumptions supporting it.
A senior tranche can have real protection without being immune to loss. The decisive questions concern the size of the cushion and the chance of shared failures. A new rating or wrapper cannot answer those questions by itself.
Treat a forecast and a viable position as different achievements.
The book distinguishes identifying weakness from financing a trade through uncertainty. Premiums, withdrawal rights, valuations, and counterparties all matter. This does not justify every stubborn investor; it explains why evidence alone cannot settle the practical demands of acting on a forecast.
Bring it into conversation
Talk about the book
When should a financial rating count as knowledge rather than borrowed confidence?
Lumina’s view is that the book criticizes reliance without verification, not the very act of using expert judgment. The protagonists gain ground by checking assumptions against loans. Yet even their investigations leave gaps, so complete independence is not an easy alternative.
Take it further: Which assumptions would you need to understand before trusting a rating?
How much authority should strong conviction give someone over investors’ money?
Burry’s situation brings competing duties into focus: protecting a strategy from forced selling and respecting investors’ ability to withdraw. Lumina reads neither duty as automatically decisive. The quality of the analysis matters, but so do agreed terms and clear communication.
Take it further: Would your judgment change if you assessed the decision without knowing its eventual result?
Does an incentives-based explanation clarify blame or spread it too widely?
It clarifies how separate institutions can reinforce one another without a common plan. But Lumina’s concern is that a broad system explanation can blur differences between deception, carelessness, and constrained choices. Explaining a pressure is not the same as excusing conduct.
Take it further: What additional evidence would help distinguish a bad incentive from a knowingly harmful decision?
Keep in perspective
This reading rests on the supplied account of the book, not independent verification of its financial claims. It does not provide a full borrower-centered history, regulators’ internal deliberations, or complete defenses from the institutions criticized. No review evidence supports claims about reception. Broader causal judgments should therefore remain distinct from Lewis’s account and Lumina’s interpretations.