
Big ideas · from the full text
The Big Short
by Michael Lewis · 4 min read · Lumina’s commentary, written with AI
- Topic: Business
About this book
The author examines the causes of the U.S. stock market crash of 2008 and its relation to overpriced real estate, bad mortgages, shareholder demand for excessive profits, and the growth of toxic derivatives.
As an Amazon Associate, Lumina earns from qualifying purchases. How this works
♫ AI-generated voice · press play below to listen and read along; tap any passage to jump to it
The crisis followed the payoffs, not just the appetites
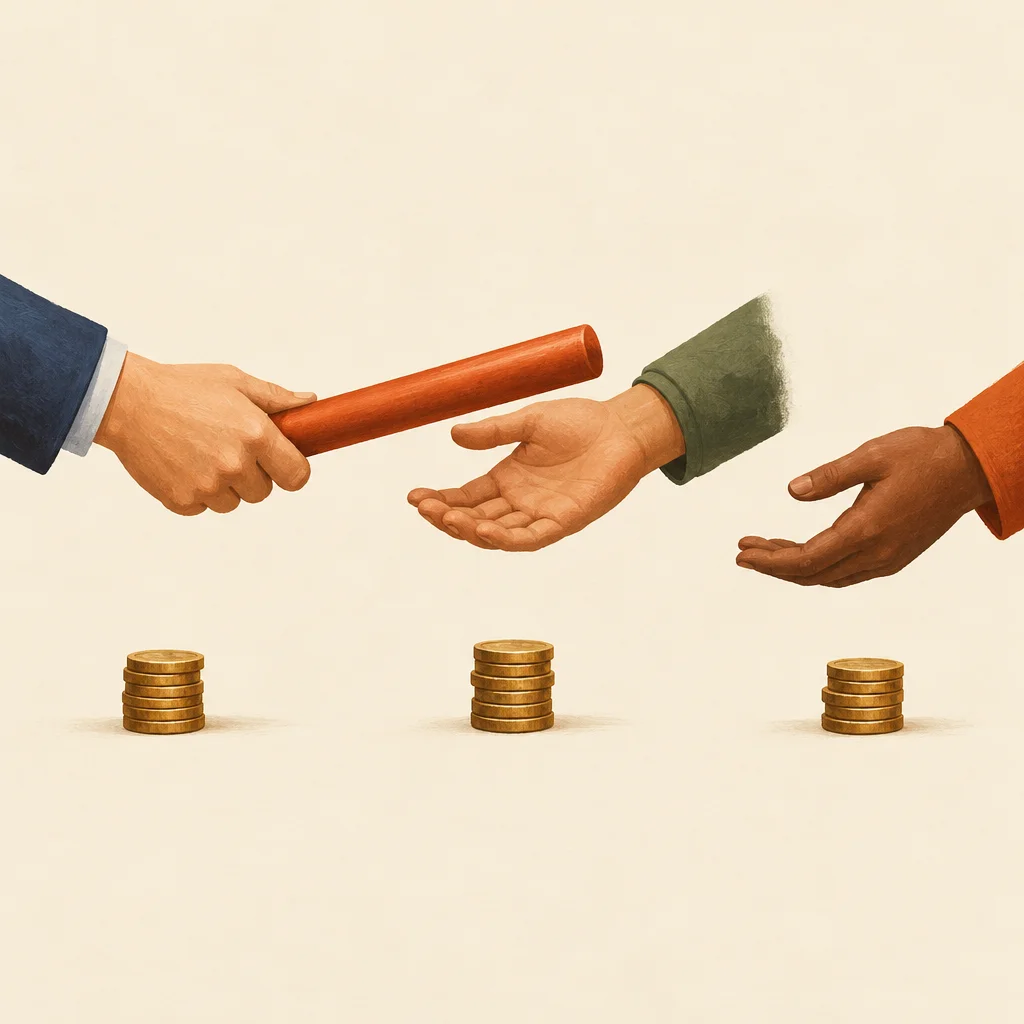
In The Big Short by Michael Lewis, the crisis is described as more than simple greed. The book emphasizes how many players could earn fees or bonuses at moments when the risk could still be shifted to someone else. One clear case is mortgage lenders who could sell mortgages after making them. If the loans failed later, that failure no longer stayed with the originator. The rewards arrived early, while losses could show up elsewhere, later.
Why it matters
This changes the blame from a few bad people to a system that paid people to pass danger onward.
An example
Lenders could sell mortgages after making them, so later loan failure did not stay with them.
Keep in mind
The summary does not give a full account of every regulator, borrower, or bank decision.
More layers did not mean more independence
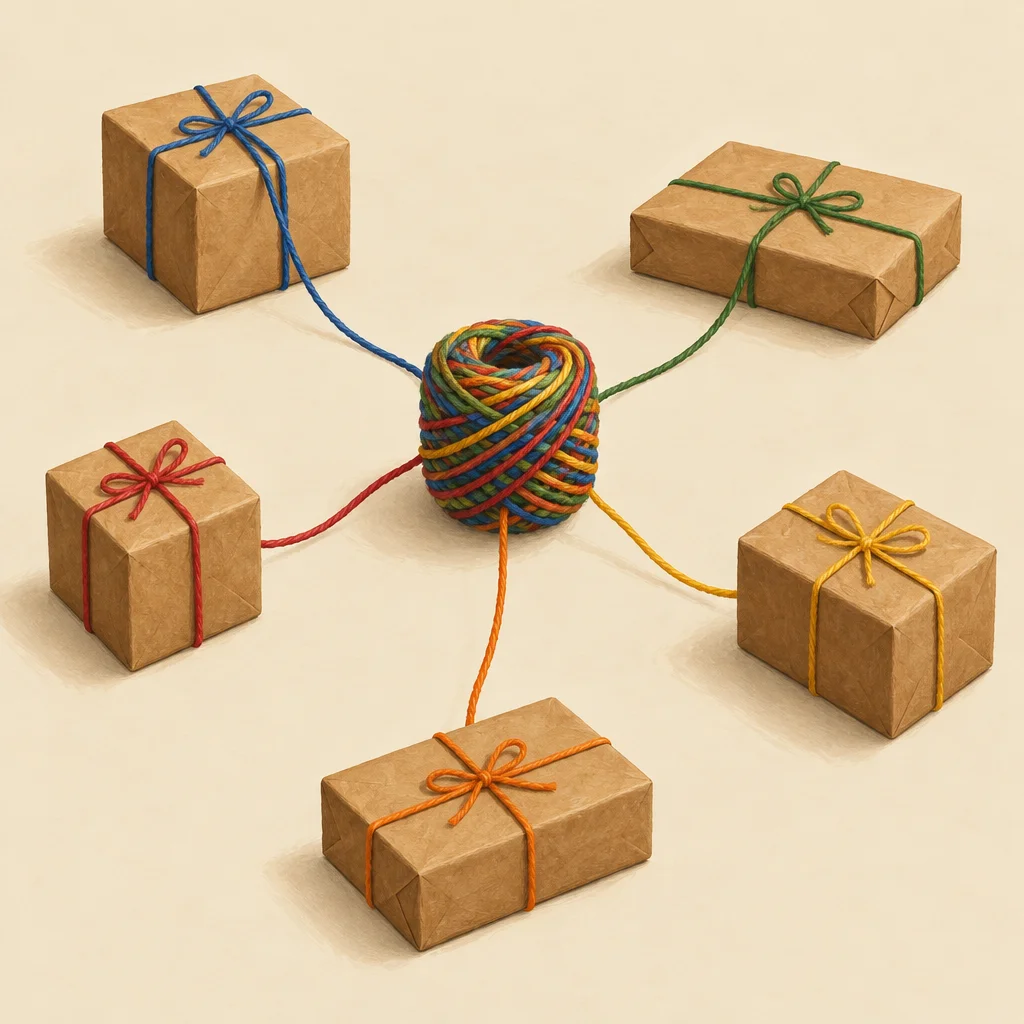
In The Big Short by Michael Lewis, structured products are shown turning housing exposure into many instruments without truly separating it. Mortgage bonds were sliced into layers, and weaker pieces were gathered into CDOs whose top layers could still receive strong ratings. Synthetic CDOs added swap contracts, which allowed repeated bets to rest on the same mortgages. The form changed, but the underlying housing outcomes still linked the risk together.
Why it matters
The book shows that risk can be multiplied even when each new label sounds safer than the last.
An example
Synthetic CDOs used swap contracts, so repeated bets could rest on the same mortgages.
Keep in mind
The supplied summary explains the basic structure, not every legal term or pricing model.
Correct didn’t mean comfortable or survivable
Contains plot details
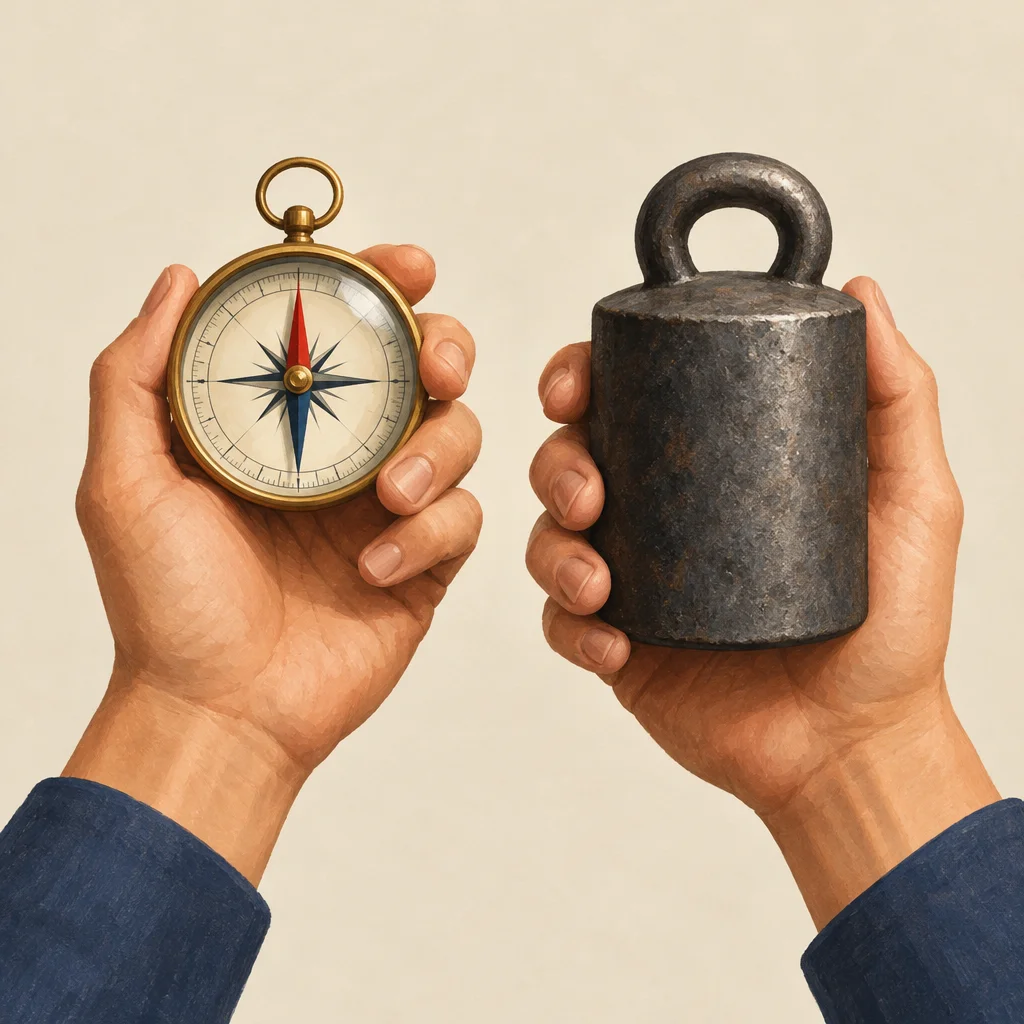
In The Big Short by Michael Lewis, identifying housing weakness early did not remove the pressures of staying in the trade. The book describes costs such as premiums, investor anger, disputed dealer marks, and concern about whether counterparties would pay. The example of investors seeking withdrawals, and Burry limiting exits from swap positions—followed by fierce pushback and legal threats—shows how analysis and endurance were separate problems. Market truth, in this account, had to be financed and tolerated long enough to matter.
Why it matters
A sound idea can still fail if contracts, clients, and cash flow cannot wait.
An example
Investors sought withdrawals; Burry limited exits from swap positions, which then brought fierce pushback and legal threats.
Keep in mind
This lesson comes from these mortgage trades; it does not prove every unpopular bet deserves patience.
A rating did not equal real scrutiny of the loans
In The Big Short by Michael Lewis, ratings appear as reassuring labels that could replace genuine knowledge of what was inside mortgage securities. The book contrasts the grade with what some investors actually examined: Burry read prospectuses, FrontPoint checked details like documentation and loan size, and Cornwall struggled to learn what CDOs held. It presents ratings that lagged rising defaults and depended on assumptions that did not match the risk within the loans. A high rating, in this account, was not the same as understanding.
Why it matters
It pushes readers to ask what evidence supports a label, not only who placed the label there.
An example
FrontPoint found weak documentation and large loans to low-income borrowers inside the mortgage machine.
Keep in mind
The summary supports criticism of ratings here, but it does not give the agencies’ complete defense.
Profit didn’t erase the system’s fragility
Contains plot details
In The Big Short by Michael Lewis, the shorts paying off is not presented as a simple victory. Even when the mortgage losses became undeniable, the book emphasizes how fragile the surrounding system felt: banks might collapse, insurers might fail to pay, and the winners’ own firms could be threatened. The example of Cornwall worrying about Bear Stearns as a trading partner and selling positions to reduce that risk shows that “winning” still depended on counterparties and financial plumbing. The payoff arrives alongside unease, not clean closure.
Why it matters
The ending turns a clever investment story into a warning about a fragile financial system.
An example
Cornwall worried about Bear Stearns as a trading partner and sold positions to reduce that risk.
Keep in mind
The source shows distress among these investors, not the full social cost of the crisis.
Liked the ideas? Read The Big Short in full.
The big ideas are free on Lumina. The complete book is available from:
As an Amazon Associate, Lumina earns from qualifying purchases. How this works