The deep dive
The Most Important Thing
by Howard Marks
18 min read · Original commentary by Lumina, written with AI
A fine business can make a poor investment, and a profitable decision can conceal serious danger. Howard Marks builds his investment philosophy around such distinctions. This deep dive examines how value, expectations, uncertainty, and survival fit together—and where his demanding reliance on judgment leaves difficult questions unresolved.
Prefer the quick version? Read the main learnings →♫ AI-generated voice · press play below to listen and read along; tap any passage to jump to it
01
An investment philosophy, not a buying signal
The Most Important Thing is nonfiction about investment judgment. It does not offer a stock screen, a trading system, or a reliable method for calling market turns. Marks instead asks how investors should reason when prices reflect other people’s beliefs and the future remains uncertain. His answer joins financial analysis with risk control, patience, and awareness of emotional pressure.
The book draws on client memos written over roughly twenty years. That origin matters to its purpose. These are connected reflections on recurring problems, rather than steps that produce a single correct answer. The title names a difficulty: several considerations can each become essential, and strength in one cannot cancel neglect of another.
Readers should therefore expect trade-offs. Lower purchase prices may provide protection, but estimates of value can fail. Holding resources in reserve can preserve future choices, but it can also mean missing gains. Independent thinking can uncover mistakes, yet independence alone proves nothing.
Lumina’s reading is that the book’s deepest subject is accountability under uncertainty. What makes a decision defensible before its result is known? Marks offers a way to examine that question without promising to remove the uncertainty that makes it necessary.
Illustrated key idea
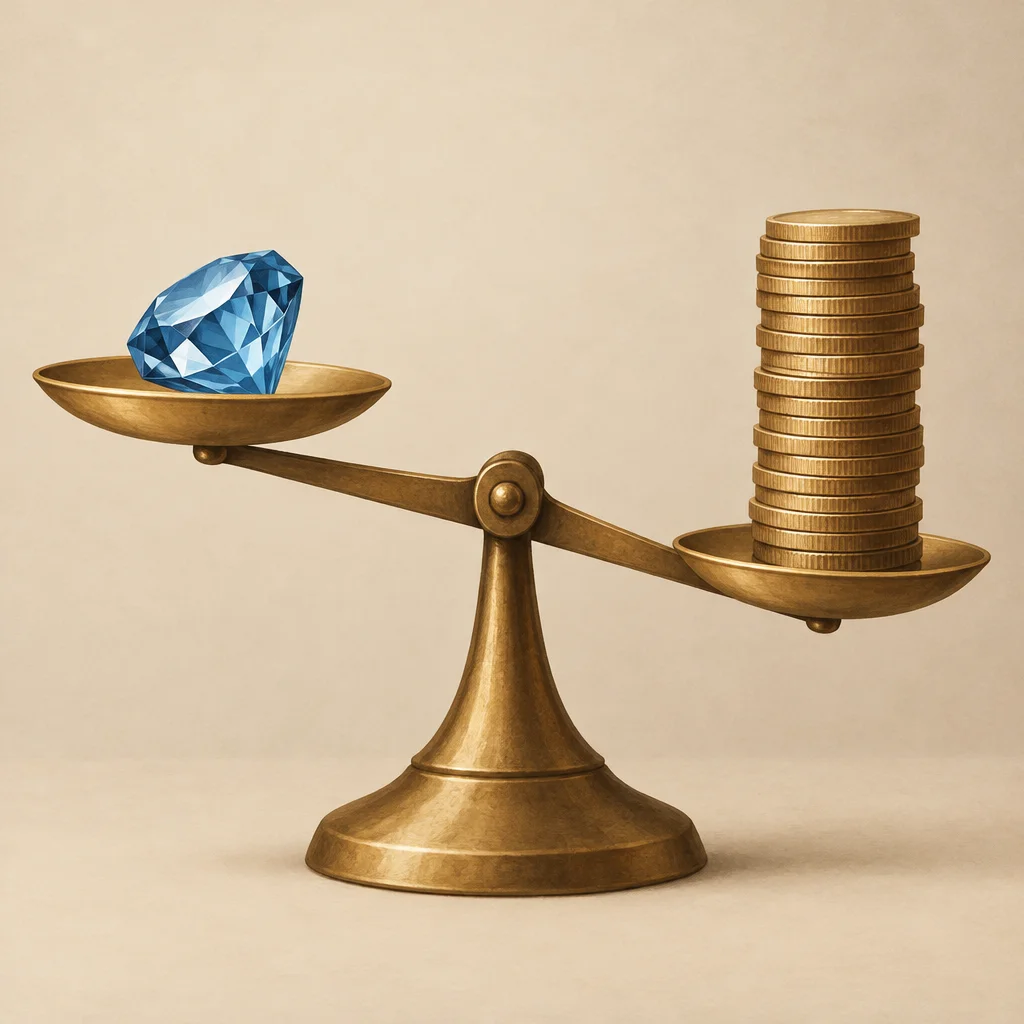
A good asset can be a bad purchase02
What counts as investing well when luck affects the score?
Marks separates three achievements that can look alike: making money, beating a market benchmark, and making sound investment decisions. A rising market can help an investor accomplish the first. Taking greater market exposure can sometimes accomplish the second. Neither result, by itself, establishes the third.
This distinction raises the book’s central question: how can investors pursue superior results without confusing favorable circumstances with skill? The stakes are practical. A person who mistakes a lucky success for a dependable method may enlarge the next bet. A manager rewarded for recent gains may accept risks whose costs remain hidden until conditions change.
Marks approaches the question from both sides of a decision. Before buying, investors should examine value, price, possible losses, and competing expectations. Afterward, they should ask how the result arose. Did it depend on a broad market rise, borrowed money, unusual good fortune, or an insight that could reasonably be repeated? The outcome matters, but the route matters too.
His distinction between beta and alpha helps organize this inquiry. Beta describes sensitivity to market movements. Alpha concerns performance beyond what that exposure explains. Yet Marks does not treat this framework as a complete measurement system. He disputes the idea that price volatility captures every important risk. Numerical comparisons still need informed judgment.
Lumina interprets the book as shifting attention from impressive scores toward defensible advantages. That does not mean good intentions excuse endless losses. Marks expects sound decisions to produce profits over time. It means that one result cannot settle whether a method deserves confidence.
The same standard applies to his own preferred style. Losing less in a downturn is not automatically evidence of skill if a cautious portfolio was built to do just that. The harder achievement is favorable performance across changing conditions, after allowing for style and risk. The book’s modest-sounding goal—meaningful gains with restrained losses—is therefore more demanding than it first appears.
03
The price tells you which future you are buying
The first central idea is that an asset and an investment are different objects of judgment. An asset has qualities: earning power, financial strength, prospects, and weaknesses. An investment adds a purchase price. Marks argues that this extra element can reverse the conclusion. Admirable assets may be poor purchases, while troubled assets may offer attractive terms.
Intrinsic value is his anchor. It means an estimate of underlying worth based on assets, earning capacity, and prospects. Without some reasoned estimate, calling a price cheap says little. A price can be lower than yesterday’s and still demand too much optimism. Equally, a price can rise while remaining below a defensible estimate of worth.
But valuation alone does not complete the task. Marks’s second-level thinking asks what others already expect and how their expectations shape the price. Knowing that a business has a promising future may offer no advantage if nearly every buyer agrees. The analytical challenge is not merely to describe the business accurately. It is to identify a meaningful difference between its likely future and the future buyers have already paid for.
Consider a hypothetical created by Lumina. Two investors agree that a company will grow. One buys because growth sounds desirable. The other asks whether the price requires growth to remain unusually strong for many years. Their business outlooks may match, yet their investment conclusions differ. The second investor is testing the terms of the purchase, not denying the company’s strengths.
The book’s Nifty Fifty example supports this distinction. Highly regarded companies did not protect buyers from severe losses when purchase prices were excessive. The lesson is not that business quality lacks value. It is that quality cannot justify every price, and confident expectations may leave little room for disappointment.
This also clarifies Marks’s qualified stance on market efficiency. Fast information processing does not ensure correct collective judgment. Still, an apparent bargain should face a demanding question: why has competition not removed it? Emotional reactions, investment restrictions, or forced transactions may supply an explanation. So may a risk the buyer has missed.
Lumina’s interpretation is that valuation and second-level thinking discipline each other. Valuation gives disagreement an anchor; attention to consensus prevents that anchor from becoming complacent self-belief. Together, they turn contrarianism from a personality trait into a claim that needs reasons.
The boundary remains substantial. Intrinsic value is an estimate, not an observable guarantee. Business conditions can worsen, assumptions can fail, and a discount can persist. A price below estimated worth offers room for error only if the estimate itself has enough support.
04
Confidence can change the danger, not just conceal it
Marks’s second major idea goes beyond warning that investors sometimes overlook risk. He argues that their confidence can help create it. When people feel safer, they may pay more, borrow more, and accept weaker protections. The belief that danger has declined can encourage behavior that makes losses more likely or more severe.
This is why he treats risk as more than price volatility. His chief concern is permanent loss of capital. He also recognizes other dangers: being unable to raise cash, failing to meet financial needs, falling behind a benchmark, or losing clients and employment. These pressures differ, but they can interact. A temporary price fall becomes harder to endure when borrowed money must be repaid or clients demand withdrawals.
Price connects this account of risk to the previous idea. If enthusiastic buyers push prices upward without comparable improvement in value, future returns become less attractive. At the same time, the cushion against disappointment shrinks. A widely admired asset can therefore become less safe precisely as more people describe it as dependable.
The credit cycle gives this reasoning a concrete mechanism. In Marks’s account, prosperity strengthens confidence among lenders. Competition then encourages cheaper financing and looser lending standards. Borrowers undertake weaker projects or carry more debt. When losses arrive, lending retreats, refinancing becomes harder, and financial strain spreads. The reversal grows partly from conditions built during the expansion.
The book points to abundant financing, weakening creditor protections, and expanding leverage before the financial crisis. Marks presents these as observable signs of vulnerability, not proof that he knew the exact course of the coming collapse. That distinction matters. A warning about fragile conditions is narrower than a successful prediction of timing, trigger, and scale.
Lumina reads this as a feedback process: beliefs influence behavior, and behavior changes the conditions being judged. Risk is not simply a fixed property waiting to be measured. Purchase prices, financing terms, and investor responses can alter it. This helps explain why a comforting record of recent stability may be a poor basis for confidence.
It also changes the meaning of diversification. Owning many securities does not provide much protection if all depend on easy refinancing or continued market confidence. Marks urges attention to shared exposures, including connections that may become stronger during stress. Counting holdings is easier than understanding what could hurt them together.
The boundary is that this account does not provide a precise risk gauge. Marks acknowledges subjective estimates, imperfect models, and uncertainty about extreme events. Nor does every optimistic market signal disaster. His claim is that complacency deserves investigation, not that anxiety reliably identifies safety. Skepticism must examine frightened beliefs as carefully as reassuring ones.
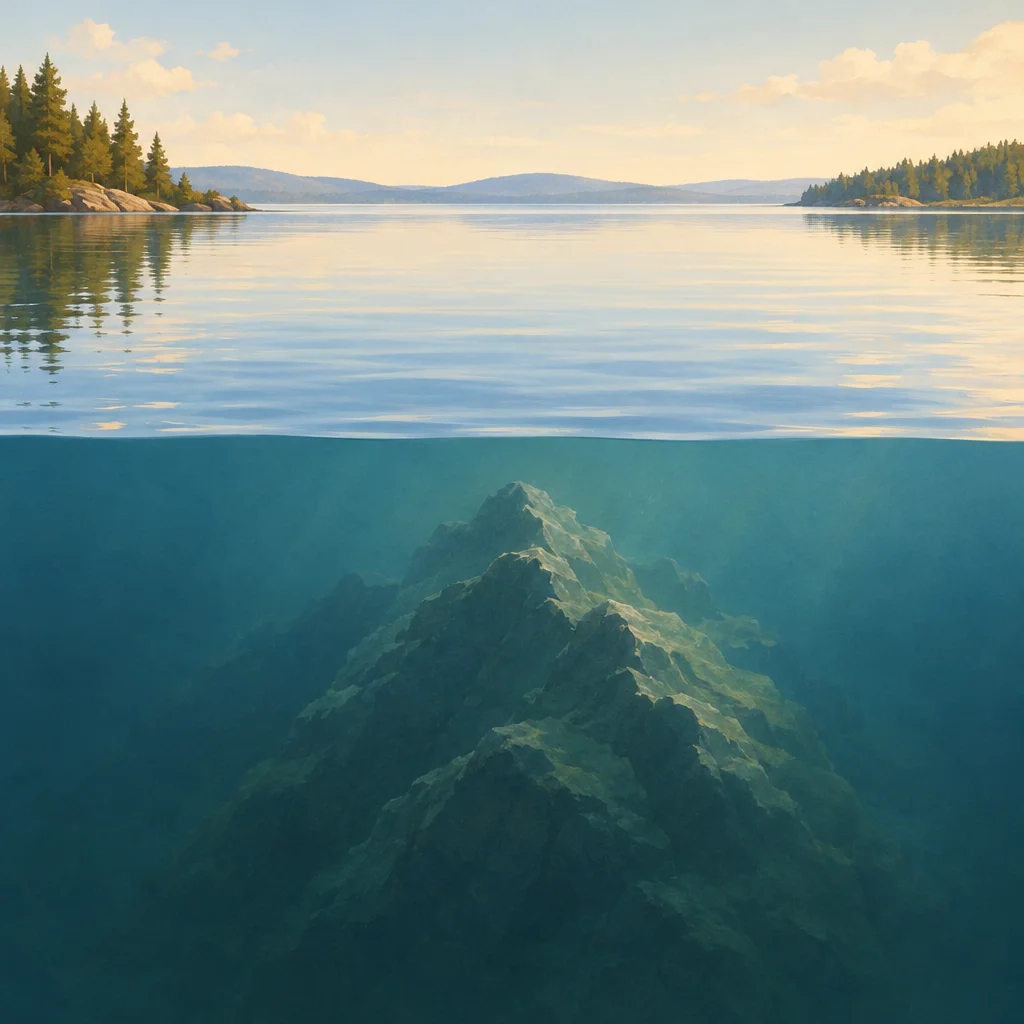
Illustrated key idea
Risk can rise when confidence rises05
Survival preserves the power to act
The third central idea turns caution into a condition for future action. Marks favors defense not because investment can become harmless, but because severe losses can remove an investor’s ability to use later opportunities. Capital protection, restrained borrowing, and dependable funding preserve choices when others have fewer.
This makes patient opportunism more demanding than simply waiting. During expensive markets, investors may have to accept lower prospective returns instead of reaching for a target the market cannot reasonably supply. They must also prepare to act when conditions become frightening. Cash or borrowing capacity has little practical value as a reserve if fear makes every possible purchase unacceptable.
Marks’s account of forced loan sales in 2008 illustrates the connection. Leveraged holders faced falling prices and demands for additional capital. Some portfolios were sold under pressure, with repayment needs taking priority over underlying worth. Prepared buyers could examine terms that sellers were not free to refuse. The opportunity depended on more than recognizing cheap assets: buyers needed resources, stable financing, and emotional endurance.
Lumina’s interpretation is that flexibility has two parts. Financial flexibility means not being compelled to sell. Psychological flexibility means being willing to revise a cautious stance when prices offer better compensation. An investor can possess one without the other. A strong balance sheet does not ensure courage, while courage cannot solve a funding crisis.
The margin of safety links this idea back to valuation. Marks wants purchases to leave room for disappointing outcomes rather than require everything to go right. Buying below a carefully assessed value is one protection. Diversification and limited leverage provide others. These safeguards address different failure routes; none makes the others unnecessary.
His emphasis on luck strengthens the argument for several layers of defense. Only one future occurs, but other plausible futures still matter when judging a decision. A gain may have depended on narrowly avoiding a damaging event. Building around several possible outcomes is therefore different from maximizing returns under one favored forecast.
The goal is an uneven balance of gains and losses: participating meaningfully when markets rise while avoiding a proportional share of the damage when they fall. Marks regards that pattern across full cycles as a demanding form of added value. It cannot be inferred from one strong year or one well-timed defensive move.
The boundary is the cost of protection. Defense may surrender gains, and excessive caution can miss genuine bargains. Marks also notes that investment types differ: avoiding defaults carries particular weight where upside is limited. Survival is his priority, not a complete instruction for every portfolio. The difficult judgment is how much protection preserves opportunity without making useful risk-taking impossible.
06
How the book makes judgment visible
The book persuades largely through distinctions, practical mechanisms, and examples drawn from investment experience. It repeatedly separates things that appear similar: a good company from a good purchase, expected returns from realized returns, caution from paralysis, and a successful result from a sound decision. These distinctions slow the reader’s rush toward a simple verdict.
Lumina’s assessment is that this method suits the subject. A formula could conceal the assumptions that Marks wants readers to inspect. By returning to the same problem from several angles, the book shows how price, psychology, funding, and risk can affect one another. The repetition has a purpose, though readers seeking a compact decision rule may find it frustrating.
Two examples carry distinct analytical weight. The technology bubble shows that a true claim about economic change need not support a particular valuation. The forced-selling examples show how a price can reflect an owner’s constraints rather than only an asset’s condition. Neither example requires the reader to believe that markets are always irrational. Each identifies a route through which judgment or transaction pressure can separate price from worth.
The evidence has limits. Marks’s examination of economic forecasting uses three surveys and is described as limited and anecdotal. It supports his skepticism within the book, but it does not establish that useful forecasting is impossible. Likewise, accounts of successful purchases illustrate how his approach can work. They do not isolate which element caused the success or prove the method will transfer unchanged.
His treatment of Oaktree adds another layer. The philosophy depends on capable colleagues, shared values, and consistent execution. This qualifies any impression that insight alone produces results. Institutions and clients must permit a strategy to remain intact while it looks unconvincing.
The strongest reason to read the original, on this account, is not to extract a hidden buying rule. It is to encounter the sustained process of weighing qualifications against conviction. The book’s form asks readers to practice holding several relevant considerations together rather than promoting one useful insight into a universal answer.
07
When does disciplined conviction become stubbornness?
Lumina’s strongest objection is that the framework may be easier to defend afterward than to use beforehand. Investors must estimate value, identify excessive sentiment, judge their own advantage, and decide how long they can wait. Each task requires the very judgment the book hopes to improve. Without a decisive test, a mistaken investor may describe stubbornness as patience and denial as independence.
The problem becomes sharp when prices keep falling. Marks says a well-founded valuation can justify holding or buying more. But falling prices may also accompany genuine deterioration. The investor must distinguish a better bargain from a damaged thesis while under financial and emotional pressure. Knowing the distinction matters is not the same as knowing which case is present.
The strongest reply, also Lumina’s interpretation, is that Marks does not offer conviction as self-validating. His framework demands analysis and eventual correctness, not simply endurance. He also recommends beginning with respect for market efficiency. An apparent opportunity needs an explanation, including a serious account of what the seller may understand better.
A related tension concerns knowledge. Marks doubts broad forecasting yet believes investors can assess present market conditions. Those tasks are not identical, but the boundary can blur. Calling financing conditions dangerously loose usually implies some concern about future consequences. The fair distinction is between identifying vulnerability and predicting exactly when or how that vulnerability will produce losses. His approach still involves forward-looking judgment; it rejects precision more than anticipation itself.
Defense creates a final challenge. A cautious style can claim vindication whenever markets decline, even if years of missed gains were costly. Marks’s own full-cycle standard supplies the best reply. Performance must be examined across favorable and unfavorable conditions, with allowances for style and exposure. Caution earns its place through the whole pattern, not through one reassuring episode.
These tensions do not make the philosophy empty. They locate its burden. The reader must remain willing to test assumptions, acknowledge opportunity costs, and recognize that a coherent explanation can still be wrong. Humility has to constrain action, not merely decorate the account given afterward.
08
Connect the questions before choosing an answer
The ideas become most useful when treated as checks on one another. Valuation asks what an asset may be worth. Second-level thinking asks what expectations the price contains. Risk analysis asks what could cause lasting damage. Funding analysis asks whether the investor can endure adverse conditions. None answers the whole investment question alone.
Lumina’s practical synthesis is to separate an investment thesis from the resources needed to hold it. A thesis can be reasonable while its financing is fragile. An asset can eventually recover while an overextended owner is forced to sell first. This is why leverage is not merely a way to enlarge returns. It can change whether the investor survives long enough for the analysis to matter.
Another connection joins patience with performance evaluation. Waiting should not be judged only by whether prices rise next week. Nor should it escape review forever. Marks’s attention to full cycles suggests examining both the opportunities forgone and the losses avoided, alongside the reasons available at the time. That is harder than celebrating either activity or restraint by itself.
For a reader assessing a manager, the book suggests questions rather than a ranking shortcut. What exposures helped produce the gains? What circumstances could produce serious losses? How does the strategy behave outside its favored environment? What evidence suggests that results exceed what its style would normally imply?
These applications remain within the book’s investing framework. They are not recommendations to buy distressed assets, hold a particular cash balance, or reject active management. Marks explicitly makes expertise, client requirements, risk tolerance, and portfolio fit relevant. The transferable habit is to connect claims with conditions: what must be true, what could fail, and what would permit continued action if events disappoint?
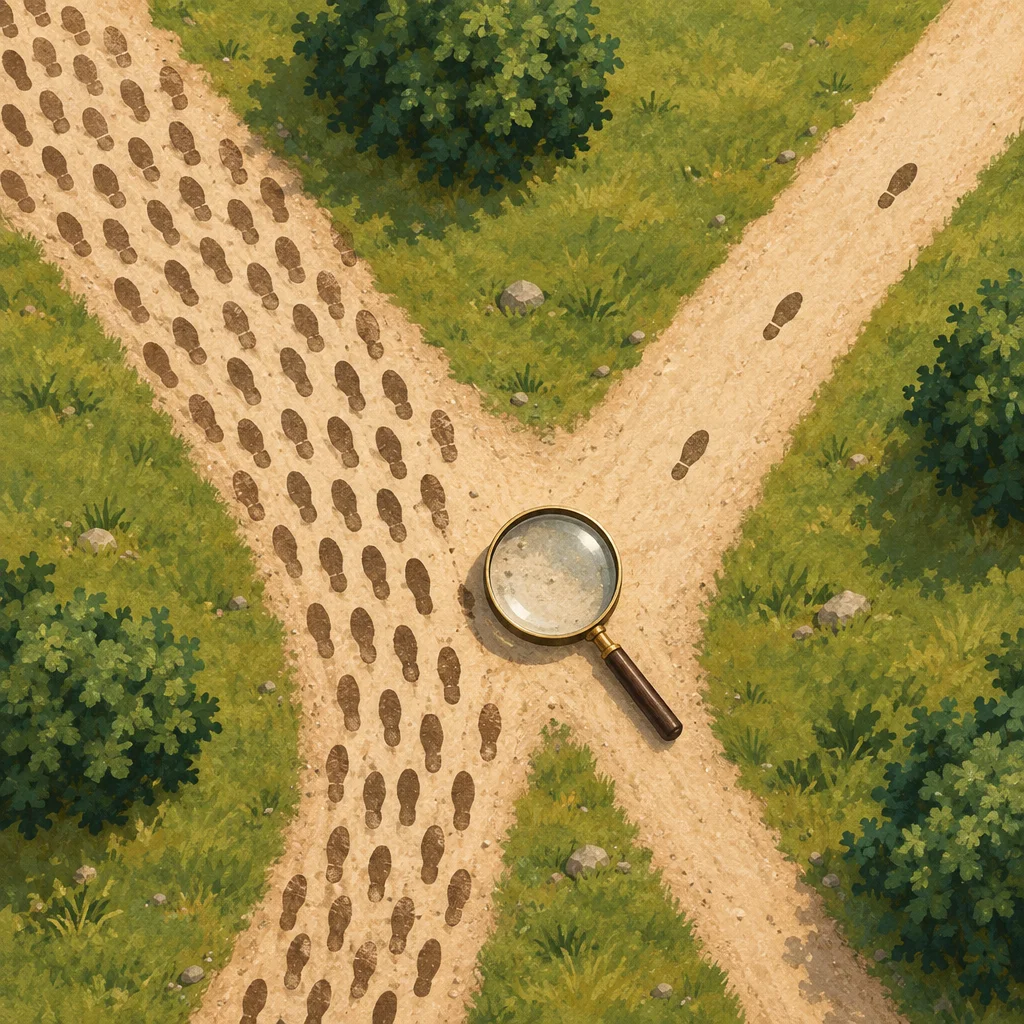
Illustrated key idea
Contrarian thinking needs a reason09
How to discuss the book without turning it into slogans
A useful discussion begins by stating Marks’s position narrowly: he favors carefully priced, risk-conscious investing while doubting dependable precision about the future. Saying that he opposes all forecasts, all growth investments, or all risk would flatten important qualifications.
One productive disagreement concerns whether valuation provides enough discipline. A supporter can argue that estimated worth offers a better anchor than recent price movement. A skeptic can reply that future assumptions remain embedded in the estimate. Both readings fit the book’s admission that conviction cannot rescue a mistaken valuation.
Another discussion can separate emotional difficulty from analytical merit. Buying during panic may feel brave, but fear alone does not establish cheapness. Refusing a fashionable investment may feel independent, but isolation does not establish insight. Ask what evidence, beyond discomfort, supports the decision.
Finally, keep the standard of success open to challenge. Marks wants meaningful participation in gains and restrained losses across cycles. Is that the right objective for every investor, or does it depend on needs and constraints? His acknowledgment of different risks and investment types gives the conversation room to develop.
These questions allow a reader to explain the philosophy and test it without claiming to have mastered valuation—or to have read every argument in the original.
What to remember
Analyze the expectations embedded in the price.
Business quality is only part of an investment case. Marks asks whether buyers have already paid for the good news. Lumina’s synthesis: a credible thesis must explain both underlying worth and why the available price offers something the prevailing view has missed.
Protection must preserve future choices.
Low prices, limited borrowing, diversification, and dependable funding address different threats. Their shared purpose is not a life without losses. It is remaining able to hold, reassess, and act when conditions worsen, while recognizing that protection itself can sacrifice worthwhile opportunities.
Judge results alongside the risks that produced them.
A gain does not reveal every danger an investor faced. Marks asks for attention to plausible alternatives and evidence across market conditions. This makes performance evaluation a study of method, exposure, and repeatability rather than a celebration of the latest return.
Bring it into conversation
Talk about the book
What would distinguish patient conviction from refusal to admit a valuation error?
Marks requires a sound estimate of worth, not confidence alone. Lumina’s view is that the difficult issue is whether new evidence changes that estimate, rather than whether the market price agrees with it.
Take it further: What kind of evidence should make an investor revise the thesis even while other investors remain fearful?
Can investors assess current market danger without making a forecast?
The book distinguishes observing weak protections or expensive prices from predicting a turning point. Yet acting on those observations still involves beliefs about possible consequences. The distinction is useful, but it does not remove judgment about the future.
Take it further: How much uncertainty about timing should a cautious investor be prepared to tolerate?
When should lower returns count as better investing?
Marks allows that a smaller return with substantially less risk may represent greater achievement. But defensive positioning alone does not prove skill. The comparison needs attention to investor needs, style, and performance across different conditions.
Take it further: Which matters more in that assessment: protection against severe loss, access to cash, or participation in rising markets—and for whom?
Keep in perspective
This discussion rests on summaries of the book, not a direct examination of its full wording, calculations, or examples. No independent reviews or external performance evidence are available here. Claims about forecasting, risk, and Oaktree’s approach are therefore presented as Marks’s arguments, not independently verified findings. The framework also cannot determine suitable investments for a particular reader.